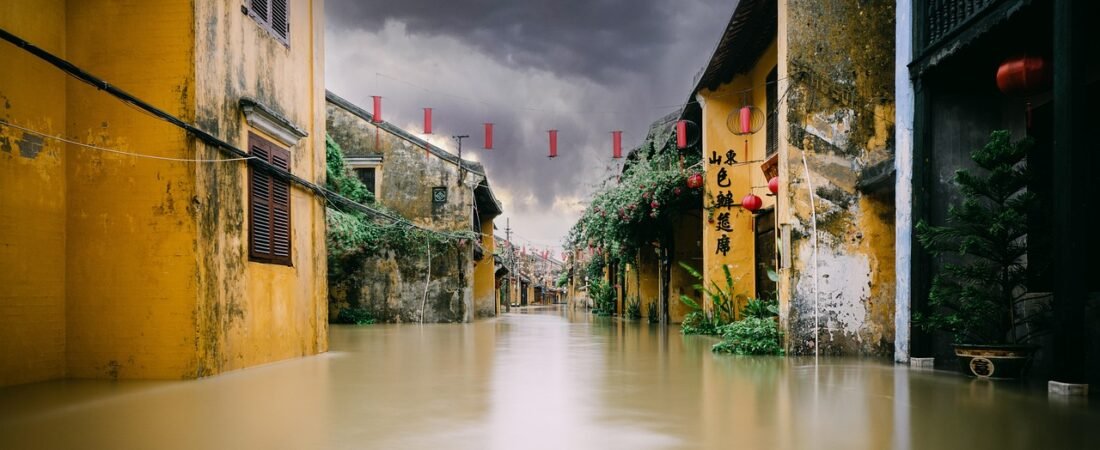
Last year, Miami-Dade County lost more residents than any other county in the United States: 72,254 people, a record high, according to Redfin’s analysis of IRS migration data. It wasn’t a hurricane season that drove them out. It was the mail. Specifically, the renewal notices that showed up in mailboxes with premiums that had doubled, tripled, or simply vanished because an insurer had stopped writing policies in the county altogether.
For years, real estate economists wondered whether Americans would ever let climate risk change where they chose to live. In 2026, the data finally says yes, but not because people are reading wildfire maps or storm-surge models. They’re reading their insurance bills. Across the country, the price of staying put in a high-risk zip code has become the clearest signal buyers and long-time owners have ever gotten, and it’s starting to rearrange the housing map county by county.
The Numbers Behind the Exodus
Redfin’s 2026 migration report found that counties with high flood risk lost a net 63,357 residents in 2025, nearly double the 34,099 net outflow recorded just a year earlier. Meanwhile, low-flood-risk counties gained 69,857 residents, their largest net gain since 2018.
The outflow wasn’t limited to Miami-Dade. Harris County, Texas (home to Houston) lost 43,377 residents. Kings County, New York, lost 38,847. Pinellas County, Florida, a low-lying peninsula that took a direct hit from back-to-back hurricanes in recent years, lost 9,203.
“Climate risk is becoming a more important factor when Americans weigh the costs and benefits of living in a certain place,” said Daryl Fairweather, Redfin’s chief economist. It’s a notably careful statement, and the data backs up the caution: only 16% of movers surveyed cited natural disaster concerns as a reason for their move, and among people who moved out of state, that figure rose to 21%. Insurance costs, not fear of the next storm itself, appear to be doing most of the persuading.
On the ground, real estate agents describe the shift in blunter terms. “If you don’t live here and you’re thinking of moving here, hurricane risk is top of mind,” said Kyle Kleinman, a Redfin agent in Miami. He’s watched relocating buyers walk away from deals not because they were scared of the water, but because the flood insurance quote made the monthly payment “through the roof.”
Insurance Premiums Are Doing the Talking
The premiums themselves explain why. According to Insurify’s 2026 rate analysis, average home insurance premiums rose for a fifth consecutive year, up 12% in 2025 alone, with some individual counties seeing spikes as high as 33% in the first half of 2026. The steepest statewide jumps this year landed in Louisiana, Michigan, Virginia, Kentucky, and Minnesota, a list that includes plenty of inland states with no coastline at all, a reminder that this is no longer purely a hurricane-belt story. Severe convective storms, hail, and wildfire risk in the Midwest and interior West are pulling premiums up in places that never used to think about “climate risk” as a homeownership line item.
The mechanics behind the increase are structural, not seasonal. Reinsurance costs, the price insurers themselves pay to spread catastrophic risk, have climbed sharply since 2023, and carriers are passing that cost straight to homeowners or exiting risky markets entirely. Realtor.com’s 2026 climate risk analysis found that National Flood Insurance Program contracts fell 4.5% year-over-year nationally, with Texas seeing a 7.8% drop in active policies and Oklahoma, Mississippi, Alabama, and even Minnesota all posting declines above 6%. Fewer active policies generally means fewer households willing, or able, to pay for the coverage a mortgage lender requires.
Where Everyone Is Going Instead
The inflow side of the ledger tells the mirror-image story. St. Johns County, Florida, gained 12,549 residents in 2025, the most of any low-flood-risk county in the country, even as its higher-risk neighbors farther south hemorrhaged population. Fort Bend County, Texas, just outside Houston but on notably higher ground, gained 10,406. Lee County, Florida, added 8,603.
The pattern that emerges isn’t “people are fleeing the Sun Belt.” It’s more specific than that: people are increasingly sorting themselves within regions, choosing the inland suburb over the coastal exposure, the elevated lot over the flood-zone one, even when both options sit in the same metro area and the same school district. Climate risk, in other words, is becoming a neighborhood-level variable in a decision that used to be made almost entirely at the city or state level.
The Affordability Math Nobody Budgeted For
Insurance is also quietly rewriting the monthly cost of homeownership everywhere, not just in the counties people are leaving. Harvard’s Joint Center for Housing Studies, in its 2026 State of the Nation’s Housing report, found that monthly costs for a median-priced home reached $3,120 in the fourth quarter of 2025, up from just $1,700 in early 2020. That figure bundles mortgage payments with property taxes and insurance, and the report specifically flags “rising insurance rates and property taxes” as a growing burden for low-income homeowners, on top of already record-high rates of housing cost burden.
The strain shows up in unexpected places, too. Homeowners association fees have climbed noticeably higher in high climate-risk areas than in lower-risk ones nationally, according to Realtor.com’s analysis, a gap driven largely by HOA-mandated master insurance policies covering shared buildings, roofs, and common areas. In some states the difference between a low-risk and high-risk community’s typical monthly HOA fee is now several hundred dollars, on top of whatever the homeowner pays for their own individual coverage.
Not Everyone Is Running Yet
It would be an overstatement to say Americans have collectively decided to abandon risk. Roughly 23.1% of U.S. homes still face severe or extreme climate risk from wildfire, storms, or flooding, per Realtor.com, and that share has held essentially flat rather than shrinking as buyers avoid those homes. When Southern California wildfires struck in early 2025, buyer interest in high-risk homes dipped only about 10% for a single month before recovering to pre-fire levels.
“Buyers are not seeking risk, but in markets where affordability has long been an issue, price is the dominant signal,” Realtor.com’s 2026 report concluded. In plain terms: when a discounted, flood-zone house is the only one a buyer can afford, the discount often still wins the argument, at least for now. Mortgage delinquency data hints at where that math eventually breaks down. Louisiana carries the nation’s highest mortgage delinquency rate at 1.7%, with Mississippi close behind at 1.4%, both well above the 0.8% national average, a early signal that in the hardest-hit insurance markets, some homeowners are already falling behind rather than moving.
What This Means for the Next Few Years
The housing market has spent decades treating location as a matter of school districts, commute times, and skyline views. Insurance underwriting is now forcing a fourth variable into that calculation, one that changes every renewal cycle and doesn’t show up on a listing photo. Counties that can offer both affordability and insurability, like St. Johns and Fort Bend, are quietly becoming the winners of a sorting process most buyers didn’t realize they’d entered.
For homeowners already in a high-risk zip code, the practical takeaway isn’t necessarily to sell. It’s to budget for insurance the way people budget for property taxes: as a number that moves every year, sometimes sharply, and increasingly deserves its own line in the household spreadsheet rather than an afterthought bundled into “housing costs.” For buyers, the lesson from 2026 is to price a home’s full insurance history, not just its climate map score, before falling in love with the discount.