The U.S. housing market just tipped further into buyer territory than at any point on record. According to new data released by Redfin on September 9, 2026, there were 57.9% more home sellers than buyers nationwide in August — the widest gap in the company’s records dating back to 2013. Combined with a separate Redfin report showing active listings at their highest level since 2020, the numbers paint a clear picture: after years of bidding wars and razor-thin inventory, the leverage has shifted, and it’s shifted hardest in the Sun Belt.
The Math Behind “Strongest Buyer’s Market on Record”
Redfin estimated 1,534,918 home sellers were active in the market in August 2026, the highest count since the start of 2020 and the largest monthly jump in sellers the company has ever recorded — up 3.9% from July. Buyer demand, by contrast, barely moved, with an estimated 972,300 buyers in the market, up just 0.1% month over month. That mismatch is what pushed 36 of the 49 major metros Redfin tracks into buyer’s market territory, or 73% of the markets analyzed. Only five metros remain seller’s markets.
“With sellers piling into the market and demand falling flat, today’s house hunters can afford to be choosy,” said Redfin Senior Economist Asad Khan, in comments accompanying the August buyer’s-market report. Khan advised buyers to “negotiate on price and ask for concessions like repairs or help with closing costs,” while telling sellers they now need to “work harder to stand out” and “price competitively from the start.”
Why the Sun Belt Is Ground Zero
The imbalance is not evenly spread across the country — it’s concentrated in the metros that boomed hardest during the pandemic-era building surge. Every one of Redfin’s ten strongest buyer’s markets in August was in the Sun Belt, and four of the ten were in Texas alone. Nashville topped the list with 139% more sellers than buyers, followed by Miami (138%), Houston (131%), Orlando (122%), Las Vegas (117%), San Antonio (116%), Austin (115%), Dallas (108%), Atlanta (95.6%) and Phoenix (94.8%).
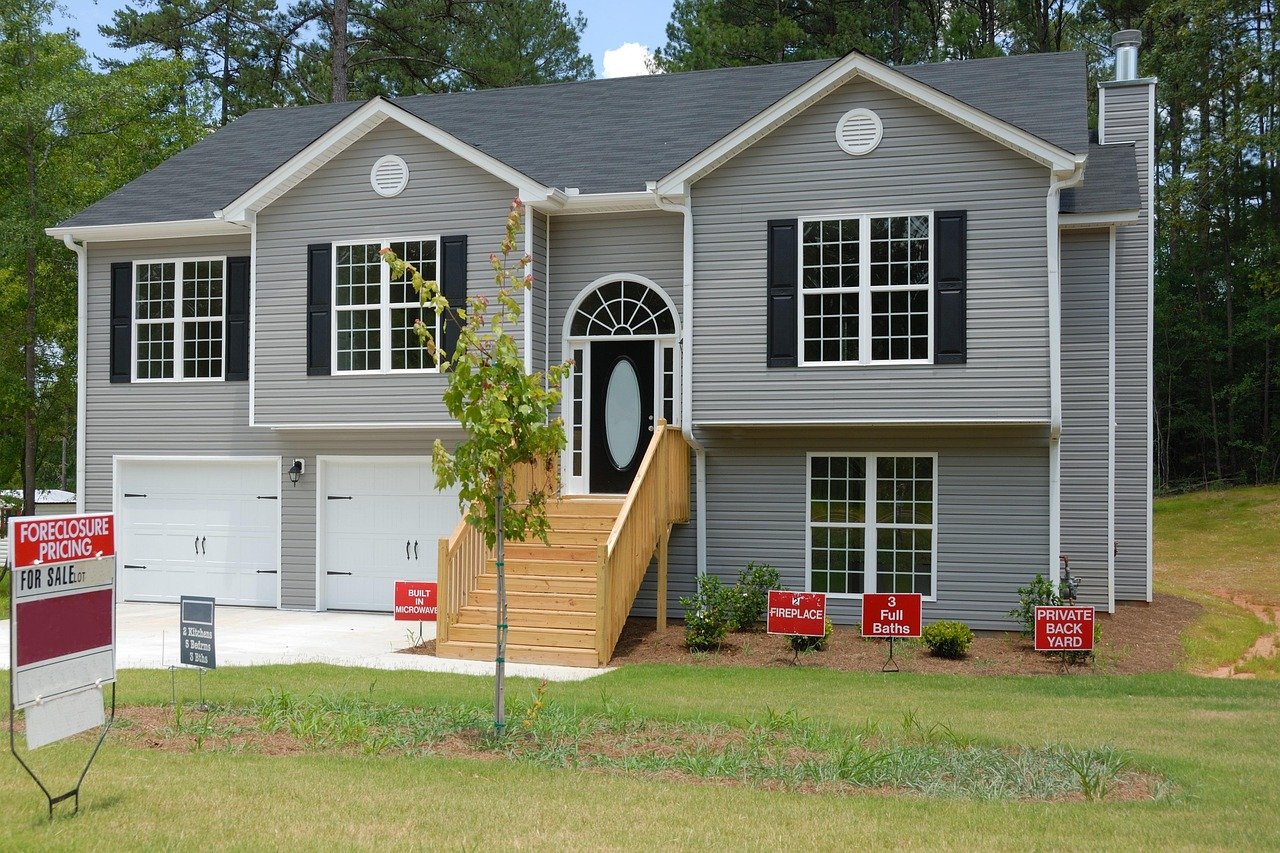
These are the same metros that saw the most new home construction between 2021 and 2024, when builders raced to keep up with pandemic-era migration. Now that new supply is landing at the same time mortgage rates remain elevated and remote-work migration has slowed, those markets are the ones absorbing the glut. Meanwhile, a handful of tightly supplied Northeastern metros are moving in the opposite direction: Nassau County, NY (28% fewer sellers than buyers), Newark, NJ (21% fewer), Montgomery County, PA (20% fewer), Milwaukee, WI (17.7% fewer) and San Francisco, CA (11.7% fewer) remain the only seller’s markets left standing. Prices in those five markets rose 5.5% year over year on average, compared with just 1.6% in buyer’s markets — a gap Khan’s team says shows how starkly local supply, not national headlines, now determines what a price tag actually does.
Supply Is Piling Up Even Faster Than Demand Is Slowing
A companion Redfin report on new and active listings, also released in September 2026 covering August data, shows the supply side of the equation accelerating. New listings rose 2.6% month over month — the biggest such jump in more than four years — and were up 4.3% from a year earlier. Active listings, the total pool of homes for sale, climbed 3.9% month over month and 2.7% year over year, reaching their highest level since 2020.
Some individual metros are seeing supply surge even faster than the national average: new listings jumped 25.5% year over year in San Jose, 15.8% in Nashville and 13.7% in Seattle, while active listings rose 24.2% in Seattle, 18.7% in Boston and 17.7% in San Jose. “More listings mean buyers can take their time, compare homes and negotiate instead of feeling pressured,” said Chen Zhao, Redfin’s head of economics research, in the listings report.
Rates Crossing 7% Are Keeping Demand Pinned Down
Part of what’s driving the imbalance is on the demand side: mortgage rates, which had drifted down through much of the summer, moved back above 7% in September. Freddie Mac’s benchmark survey put the average 30-year fixed rate at 7.03% for the week of September 24, 2026 — the first time it had crossed that threshold in well over a year, according to NPR’s coverage of the Freddie Mac data. For a household already stretched by years of high home prices, a rate back above 7% is enough to keep plenty of would-be buyers on the sidelines even as sellers keep listing, which helps explain why Redfin’s buyer count barely budged in August while the seller count jumped by its largest margin on record.
What Sellers Are Actually Getting Paid
The pricing data backs up the shift in power. Nationally, homes sold in August 2026 for a median of $398,596, up a modest 2.2% year over year — far below the double-digit gains common earlier in the decade. The average sale-to-original-list-price ratio was 96.4%, meaning the typical seller is accepting roughly 3.6% less than their original asking price. Nearly six in ten homes sold — 59.5% — went for below their original list price. Total supply nationally sat at 3.9 months, unchanged from the prior month, while closed home sales actually dipped 0.5% month over month, the slowest pace of closings in more than a year, even as pending sales stayed essentially flat.
Put together, those numbers describe a market where inventory is building, closings are slowing, and sellers who don’t adjust their price expectations quickly are the ones left sitting with a “Days on Market” counter that keeps climbing. It’s a dramatically different dynamic from the multiple-offer, waived-inspection climate of 2021–2022, and it’s arriving at a moment when many households had assumed that kind of leverage for buyers was gone for good.
What This Means
If you’re house hunting this fall, the data suggests you have more room to negotiate than at almost any point in the last decade — but that room is unevenly distributed. In Sun Belt metros like Nashville, Miami, Houston, Austin or Phoenix, buyers can reasonably ask for price cuts, seller-paid closing costs, repair credits or rate buydowns, and sellers in those markets should expect to grant at least some of it. In the handful of remaining tight markets — parts of greater New York, suburban Philadelphia, Milwaukee and San Francisco — that leverage largely doesn’t apply, and competitive offers are still the norm.
For sellers anywhere, but especially in Sun Belt metros with heavy new construction, the practical takeaway from Redfin’s economists is blunt: price at or slightly below recent comparable sales from the start, rather than testing the market high and cutting later. With supply still climbing into early fall and the buyer pool essentially flat, homes priced ambitiously are the ones most likely to sit — and every week on market tends to erode a seller’s negotiating position further. Whichever side of the transaction you’re on, the underlying lesson from this data is the same one real estate agents have been repeating all year: national headlines about “the housing market” mean very little compared with what’s actually happening in your specific zip code.